
Buying Property From an NRI in Mohali 2026 is about to become administratively easier—but not tax-free, risk-free or identical to buying from a resident Indian seller.
A major Income Tax change takes effect from:
1 October 2026
for a resident individual or Hindu Undivided Family buying immovable property from a non-resident seller.
Until now, such a buyer generally needed to obtain a:
Tax Deduction and Collection Account Number — TAN
to deduct and report tax on the payment to the NRI seller.
From 1 October 2026, the Income Tax Department’s official Budget 2026 guidance says that specified resident individual/HUF buyers will no longer need to obtain TAN solely for such an immovable-property transaction.
Instead:
the buyer’s PAN will be used for the deduction/reporting mechanism, with the seller’s PAN quoted in the challan-cum-statement.
That is a meaningful compliance simplification.
But it creates an equally important risk of misunderstanding.
The change does not mean:
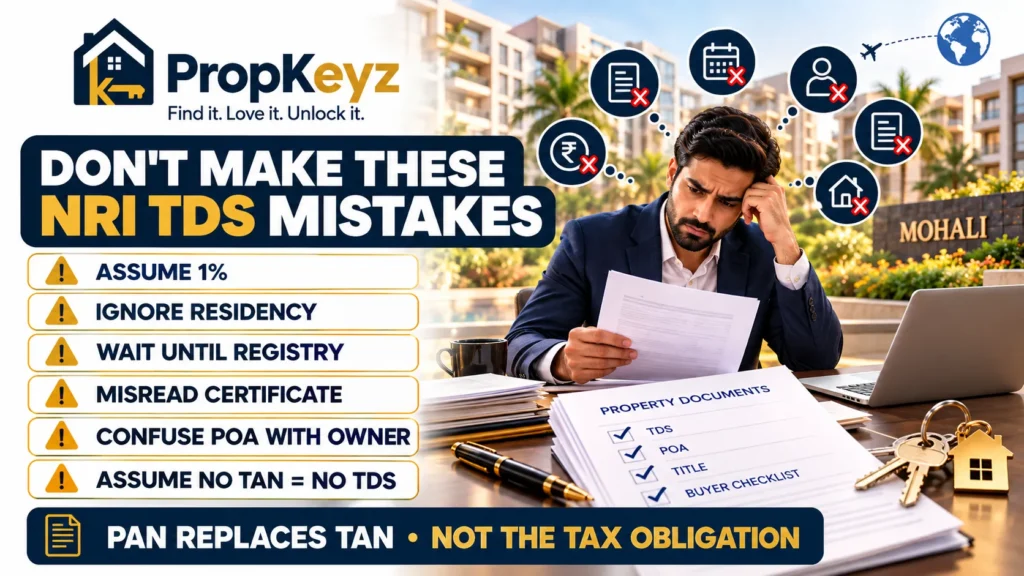
“NRI property par ab normal 1% TDS hai.”
It also does not mean:
“October 1 ke baad TDS khatam.”
The central rule remains:
PAN replaces the TAN requirement for the specified buyer. It does not replace the NRI withholding rules.
For a Mohali buyer evaluating an NRI-owned:
- Aerocity flat
- IT City apartment
- Sector 66 property
- Airport Road resale
- GMADA plot
- builder floor
- independent house
- Zirakpur or Kharar investment property
the tax process should be checked before token/payment milestones are fixed, not after the sale deed is ready for registration.
This PropKeyz guide explains what changes on 1 October, what does not change, why the normal 1% property TDS rule can be dangerous in an NRI transaction, how lower-deduction certificates work, and what title, POA, society, authority and property documents should be verified before paying an NRI seller.
Last fact-checked: 24 September 2026
Key Takeaways
- From 1 October 2026, a resident individual/HUF buyer will not need TAN solely to deduct TDS on consideration paid for immovable property to a non-resident seller.
- The buyer will use PAN-based reporting under the new mechanism.
- The seller’s PAN remains important.
- The reform removes a compliance step; it does not eliminate TDS.
- The normal resident-seller rule of 1% above the applicable ₹50 lakh threshold should not be blindly applied to an NRI seller.
- Seller tax residency is determined under Income Tax law—not merely by citizenship, passport, Aadhaar or overseas address.
- “Section 195” is still widely searched and used as legacy terminology, but the Income-tax Act, 2025 has been in force since 1 April 2026. The current corresponding provisions are primarily Sections 393, 395 and 397.
- An NRI seller may be able to obtain a lower/nil-deduction certificate where justified.
- Under the current 2026 rules, Form 128 corresponds to the old Form 13 lower/nil-deduction application.
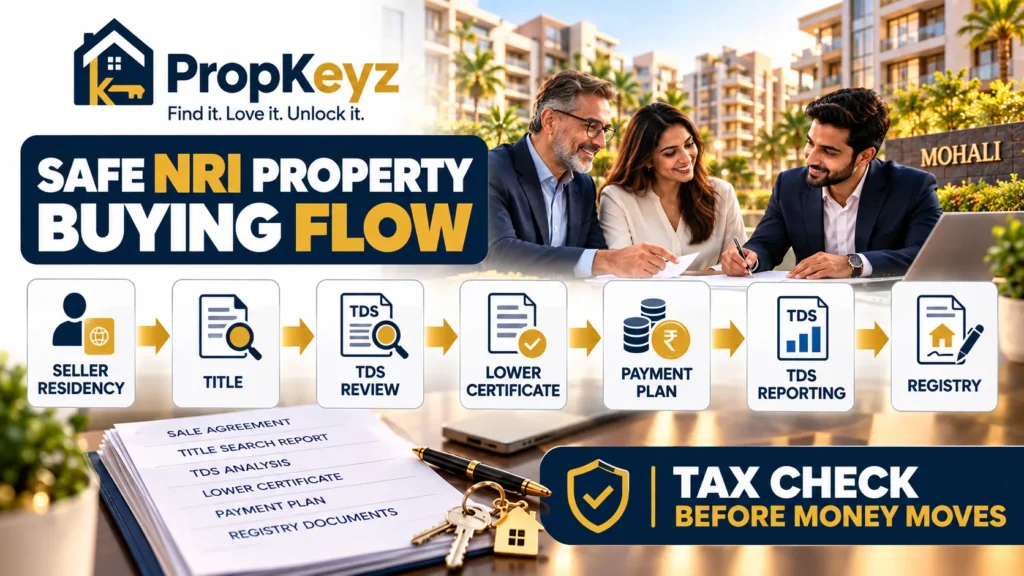
- The TDS process should be settled before the buyer releases consideration.
- Tax compliance does not replace:
- title verification
- POA verification
- society dues
- authority dues
- project/RERA checks
- possession verification.
- A smoother TDS mechanism may reduce transaction friction in NRI resales, but it does not guarantee a rise in Mohali property prices.
PropKeyz Rule
PAN replaces TAN. It does not turn an NRI seller into a resident seller.
Buying Property From an NRI in Mohali 2026: Quick Answer
From 1 October 2026, a resident individual or HUF buying an immovable property from a non-resident seller will no longer need to obtain TAN solely for deducting tax on that transaction.
The buyer will instead use:
PAN-based deduction/reporting
under the new process.
But:
the NRI withholding obligation remains.
The ordinary resident-seller:
1% / ₹50 lakh
property-TDS rule is a different provision and should not automatically be used when the seller is non-resident.
The Simplest Way to Remember It
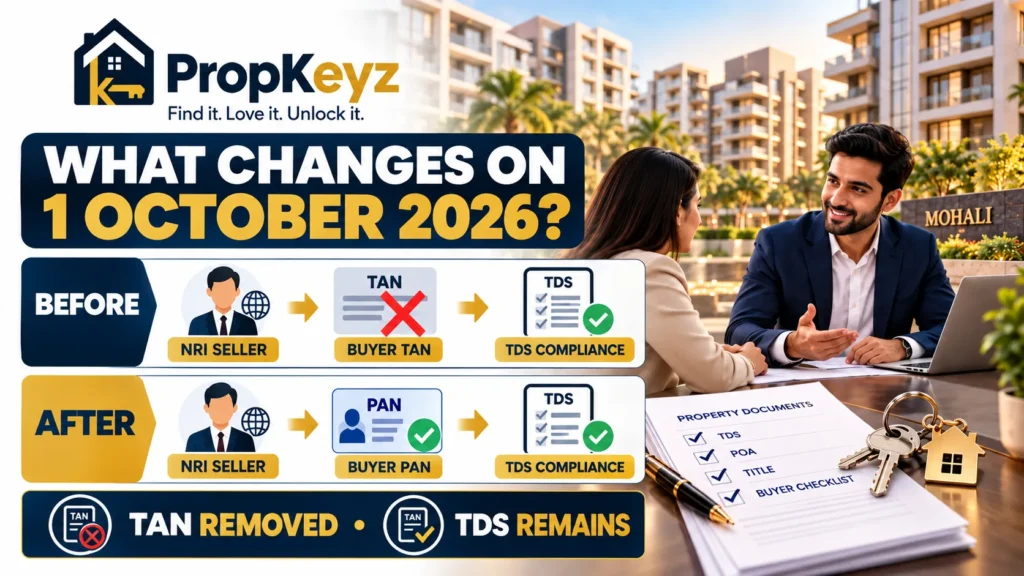
Before 1 October 2026
Resident individual/HUF buyer
→ NRI seller
→ TDS obligation
→ TAN required under the existing process.
From 1 October 2026
Resident individual/HUF buyer
→ NRI seller
→ TDS obligation remains
→ TAN not required for this transaction
→ PAN-based reporting.
Most Important Buyer Rule
Do not release the payment first and ask the CA later.
What Exactly Changes on 1 October 2026?
The government’s official Budget 2026 FAQ explains the reason for the reform.
For a resident seller, an individual/HUF buyer could already report qualifying property TDS using PAN without obtaining TAN.
But when the seller was non-resident, the buyer had to obtain TAN even if the TAN was needed for only this one transaction.
The government described this as an:
unnecessary compliance burden.
From 1 October 2026, the law removes that requirement for a resident individual/HUF buying immovable property from a non-resident seller.
What Becomes Easier?
One administrative step disappears:
separate TAN application.
What Does Not Disappear?
- seller residency check
- correct withholding calculation
- tax deduction
- tax reporting/payment
- seller PAN
- property due diligence.
Before vs After October 1, 2026
| Issue | Up to 30 Sep 2026 | From 1 Oct 2026 |
|---|---|---|
| Seller | Non-resident | Non-resident |
| Buyer covered by reform | Resident individual/HUF | Resident individual/HUF |
| TDS obligation | Yes | Yes |
| Separate TAN requirement | Yes under existing process | No for covered buyer |
| Buyer PAN | Required | Used for reporting |
| Seller PAN | Important | Important |
| NRI withholding framework | Applies | Still applies |
| Normal 1% resident-seller rule | Not automatically applicable | Still not automatically applicable |
| Property title checks | Required | Required |
| CA/tax review | Recommended | Recommended |
What This Table Really Means
Compliance becomes simpler. Tax classification does not change.
Section 195 vs Sections 393, 395 & 397 — Why You May See Different Numbers
Many buyers, brokers and even older government guides know NRI property withholding as:
Section 195 TDS.
That terminology comes from the former Income-tax Act, 1961.
However, the Income-tax Act, 2025 came into force on 1 April 2026 and replaced the old Act.
Under the current law:
Section 393
Deals with deduction of tax, including payments/sums chargeable to non-residents.
Section 395
Contains mechanisms around:
- lower/nil deduction
- appropriate taxable portion.
Section 397
Deals with:
- PAN
- TAN
- compliance/reporting identifiers.
The October 1 reform appears in the current Section 397 framework for a resident individual/HUF buying immovable property from a non-resident.
Why This Article Still Uses “Section 195”
Because buyers still search phrases such as:
- NRI property Section 195
- Section 195 TDS property
- buy property from NRI Section 195.
PropKeyz Rule
Know the old terminology—but follow the current law.
Resident Seller vs NRI Seller: Do Not Mix the Two
This is the biggest practical risk.
Resident Seller
The ordinary property-TDS framework for a qualifying resident seller provides:
1%
on the consideration or stamp-duty value, whichever applies under the provision, where the statutory ₹50 lakh threshold is met.
Non-Resident Seller
The non-resident payment framework is different.
Current Section 393(2), Table Sl. No. 17 covers:
other sums chargeable under the Act paid to a non-resident
at:
rates in force.
Therefore
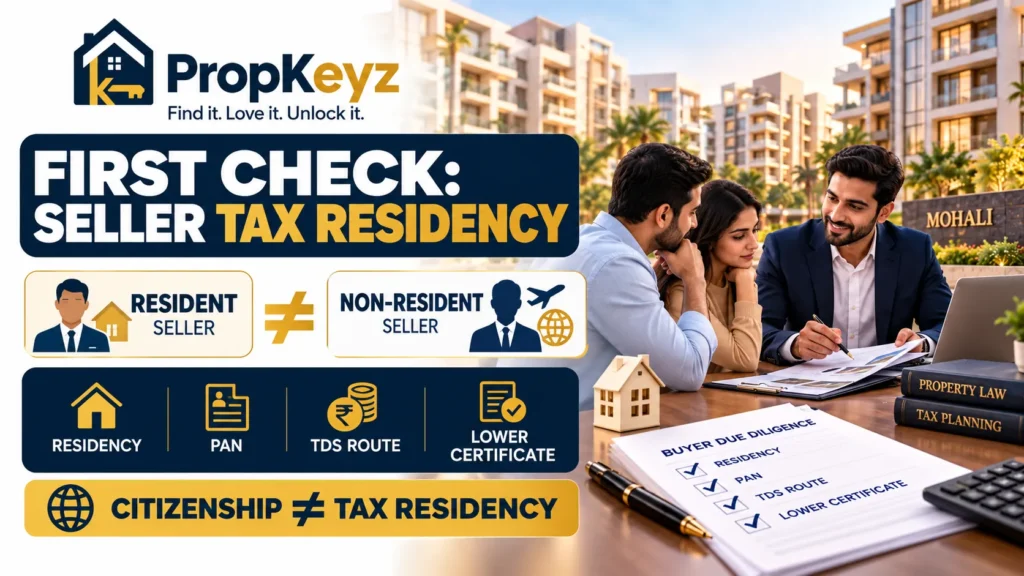
Resident seller TDS ≠ NRI seller TDS
Why Blindly Deducting 1% Can Become Expensive
Suppose a buyer purchases a Mohali apartment.
The seller:
- has an Indian PAN
- has an Indian passport
- owns property in India
- speaks to the buyer through an Indian broker.
Buyer assumes:
“Indian seller hai.”
Then deducts:
1%.
But the seller’s tax residential status for the relevant year is actually:
non-resident.
Now the buyer may have followed the wrong withholding route.
A recent tax-litigation report highlighted buyers who used the resident-property TDS route where the seller later turned out to be non-resident, leading to additional tax, interest and penalty proceedings before relief was eventually considered on the facts.
Practical Lesson
Seller nationality ≠ seller tax residency.
How Do You Know Whether the Seller Is NRI?
Income Tax law determines residential status principally through statutory residence tests for the relevant tax year.
The Income Tax Department’s current guidance includes tests based on:
- days of stay in India during the tax year
- days of stay during preceding years
- special rules for Indian citizens / persons of Indian origin
- deemed-residency provisions in specified situations.
Buyer Should Not Guess From:
- passport
- Aadhaar
- foreign address
- WhatsApp number
- where seller says they “live.”
Practical Buyer File
Ask for:
- seller PAN
- written residential-status declaration
- overseas address/contact
- transaction-year confirmation
- CA confirmation where appropriate.
For a high-value transaction, tax residency should be confirmed professionally.
Is There a ₹50 Lakh Threshold When Seller Is NRI?
This is another dangerous assumption.
The well-known:
₹50 lakh threshold
belongs to the ordinary resident-seller immovable-property TDS provision.
The Income Tax Department’s non-resident TDS guidance states that taxable payments to non-residents generally do not enjoy the same ordinary threshold exemption.
Therefore
Do not say:
“Property ₹45 lakh hai, TDS nahi lagega.”
merely because that would be the resident-property logic.
PropKeyz Rule
First identify seller residency. Then identify the applicable tax provision.
When Does the Buyer Deduct TDS?
The current non-resident withholding framework generally looks to deduction at the earlier of:
- credit
- payment
for the relevant taxable sum.
For property transactions with:
- token
- advance
- instalments
- final registration payment
the timing can therefore matter.
Buyer Mistake
“Registry ke din CA dekh lenge.”
But substantial consideration may already have been paid before registration.
Better Process
Set the tax workflow:
before the payment schedule starts.
How Much TDS Is Deducted From an NRI Seller?
There is no responsible one-line answer for every transaction.
Income Tax Department’s current FAQ notes that:
Long-Term Property Gain
For transfers on or after 23 July 2024, the underlying long-term capital-gains rate referenced in its current guidance is:
12.5%
subject to applicable tax rules.
Short-Term Gain
For a non-resident individual/firm, current guidance references:
30%
for short-term capital gains.
Applicable:
- surcharge
- health and education cess
- other tax provisions
can also matter.
Very Important
Do not use the above as:
“Just deduct 12.5% of the sale price.”
The correct amount on which tax should be withheld can require professional determination.
Buyer Rule
Rate question + taxable-sum question must both be answered.
Why NRI Sellers Often Seek a Lower-Deduction Certificate
Suppose:
Sale price = ₹1.20 crore
But the seller’s actual taxable capital gain is materially lower because of:
- original purchase cost
- applicable tax computation
- eligible adjustments/exemptions.
If withholding is applied mechanically at a high rate on the full transaction amount, the seller can face:
significant cash-flow blockage.
That is why lower/nil-deduction mechanisms exist.
Lower / Nil TDS Under Current 2026 Law
Under current Section 395, an eligible taxpayer may seek a certificate allowing:
- lower deduction
- nil deduction
where the statutory conditions justify it.
Under the Income-tax Rules, 2026, the current lower/nil-deduction application is:
Form 128
which corresponds to the former:
Form 13.
Important for Brokers and Buyers
You may still hear:
“Seller ne Form 13 apply kiya hai.”
In current 2026 terminology:
Form 128 is the corresponding new form.
Can the Buyer Seek Determination of the Taxable Portion?
The current forms framework also provides Form 15E for a person seeking determination of the appropriate proportion of a sum payable to a non-resident that is chargeable to tax under the current Section 395 framework.
This is a specialised tax process.
PropKeyz Position
PropKeyz should not:
- calculate this itself
- advise the buyer on the taxable proportion
- promise a particular withholding rate.
Use:
qualified CA/tax professional.
October 1 Portal Warning — Do Not Assume the Screen Is Already Live
This is extremely important as of 24 September 2026.
The government’s Budget FAQ clearly says the PAN-based TAN exemption becomes effective from:
1 October 2026.
However, the current Income Tax e-filing help page for Form 141, checked on 24 September, still says:
the form cannot currently be filed where the deductee is non-resident.
What Does That Mean?
The legal change is confirmed.
But the live portal workflow for the new NRI-property PAN process should be checked:
on or after 1 October 2026
before a buyer follows any old screenshot or YouTube tutorial.
Do Not Do This
“Form number pata hai, payment kar do.”
Do This
Confirm current portal instructions with:
- Income Tax e-filing portal
- CA/tax adviser.
What If There Are Multiple Buyers or Sellers?
Property transactions can involve:
- husband + wife buyers
- siblings
- co-owners
- multiple NRI sellers.
Do not assume the paperwork becomes:
one buyer + one seller
simply because there is one property.
Tax and reporting obligations should be mapped to:
- actual buyers
- actual sellers
- ownership shares
- payment shares.
Use the current Income Tax process applicable on the transaction date.
Buying From an NRI Through Power of Attorney
Many Mohali NRI properties are sold while the owner remains in:
- Canada
- UK
- UAE
- USA
- Australia.
A representative may appear through a:
Power of Attorney.
Buyer Must Check
- original owner identity
- current ownership
- POA authenticity
- execution/authentication
- property covered
- power to sell
- power to receive money, if claimed
- whether POA has been revoked
- current validity.
Most Important Rule
POA holder ≠ owner.
The owner remains the principal unless the underlying transaction/document establishes otherwise.
For broader remote-owner protection and POA awareness, read:
Mohali NRI Property Protection 2026
Tax Compliance Does Not Replace Title Verification
A buyer can deduct every rupee of TDS perfectly and still buy:
a legally problematic property.
Before purchase, verify:
Seller
- exact registered owner
- PAN
- tax residential status
- POA if used.
Title
- sale deed/conveyance
- previous chain where appropriate
- mutation/revenue record where relevant
- encumbrance/mortgage.
Property
- exact flat/plot
- parking rights
- possession
- boundaries where relevant.
Project
For applicable project property:
- RERA
- sanctioned project/phase
- builder/authority records.
Dues
- society
- maintenance
- utility
- authority.
For remote-owner property-record checks, read:
NRI Property Record Monitoring Tricity 2026
Mohali Property Record Checks Matter Especially in NRI Resales
An NRI seller may have purchased the property:
- 5 years ago
- 10 years ago
- during project launch
- before moving overseas.
Since then there may have been changes involving:
- conveyance
- mutation
- society formation
- bank mortgage
- authority dues
- project completion.
Buyer Should Ask
What is the current record—not only the original purchase file?
That is especially important in:
- old investor-held flats
- vacant NRI properties
- long-held plots
- inherited properties.
What About GMADA / CLU / Project Approvals?
For a private/project property, tax compliance does not prove project legality.
A project can separately require checks involving:
- title
- CLU
- licence
- layout
- RERA.
For deeper Mohali planning due diligence:
PropKeyz Rule
NRI seller status is a tax question. Project approval is a property question. Check both.
Society NOC / Dues Before NRI Resale
For apartment transactions, obtain clarity on:
- maintenance dues
- move-out/transfer process
- parking
- society records
- tenant status
- key/access cards.
If Property Is Rented
Also identify:
- tenant
- agreement
- possession date
- notice period
- security deposit
- handover plan.
A sale agreement should not assume:
vacant possession
unless the property can actually be handed over vacant as agreed.
Bank Loan / Mortgage Check
An NRI-owned property may still have:
- bank loan
- equitable mortgage
- lender documents.
Buyer should verify:
- outstanding loan
- release process
- original-document custody
- bank NOC/release where applicable.
Why?
Payment should be structured around:
clear discharge and document release.
Token Money: Do Not Pay First and Investigate Later
The buyer’s weakest position is often:
after a large non-refundable token is already paid.
Before token or before making it substantial, verify at minimum:
- seller identity
- ownership
- seller residency
- property details
- major dues
- mortgage
- POA if applicable
- obvious litigation/issues
- TDS plan.
Add a Clause
The agreement/token receipt should appropriately address:
- seller cooperation for tax documents
- residential-status information
- lower-deduction certificate if applicable
- outstanding dues
- original documents
- title/POA.
Use a qualified lawyer for drafting.
NRI Seller Checklist
An NRI seller should organise:
- PAN
- tax-residency information
- purchase deed
- cost documents
- current ownership record
- POA if applicable
- lower/nil deduction certificate if obtained
- society/authority dues
- bank loan status
- possession/tenant information.
Why?
A buyer who sees a clean file is less likely to stop the deal at the last moment.
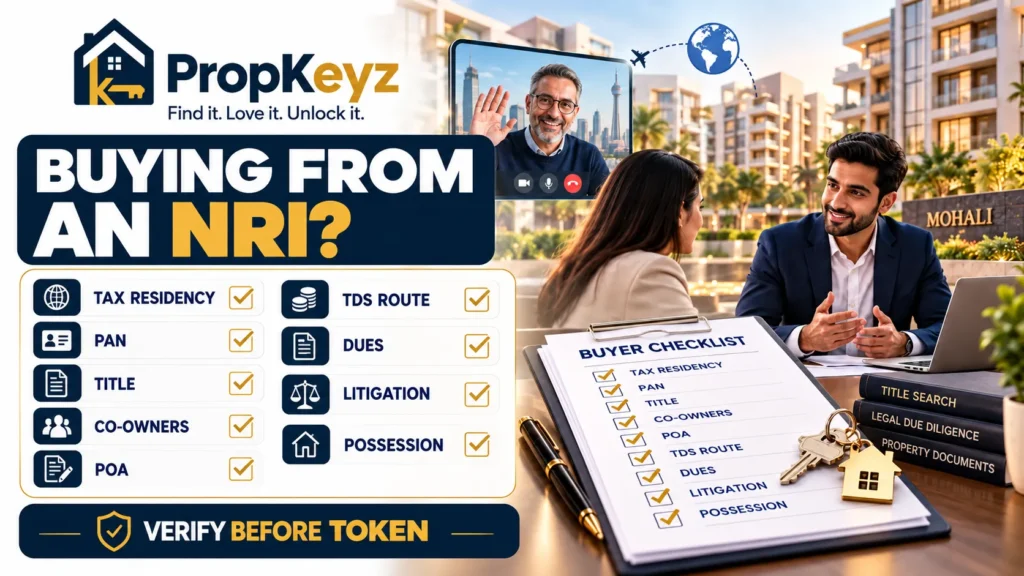
Buyer Checklist Before Buying an NRI-Owned Mohali Property
Seller
- Seller full name?
- PAN?
- Tax resident or non-resident?
- Written declaration available?
- Multiple sellers?
Tax
- Correct withholding provision?
- Transaction before or after 1 October 2026?
- Is buyer covered by PAN/TAN reform?
- Lower/nil certificate?
- CA reviewed payment schedule?
- Portal process checked live?
Ownership
- Seller name matches title?
- Sale/conveyance deed?
- Mutation/revenue record where applicable?
- Mortgage?
POA
- Seller personally signing?
- If POA, does it authorise sale?
- Execution/authentication checked?
- Revocation checked?
Project / Property
- Exact flat/plot?
- RERA where relevant?
- CLU/licence where relevant?
- Parking?
- Possession?
Dues
- Society?
- Maintenance?
- Electricity/water?
- Authority?
- Bank?
Handover
- Vacant?
- Tenant?
- Keys?
- Original documents?
- Meter readings?
- Access cards?
Does the October 1 Change Increase Mohali Property Prices?
Not directly.
This is a:
transaction-friction reform
rather than:
a property-demand subsidy.
Before
NRI resale
→ TAN requirement
→ extra compliance step
→ buyer hesitation possible.
From October 1
NRI resale
→ PAN-based route for specified buyer
→ one administrative step removed
→ potentially smoother transaction.
Property Science
Compliance Friction ↓
→ Buyer Convenience ↑
→ NRI Resale Execution Can Improve
But:
Convenience ≠ automatic appreciation.
Rates will still depend on:
- location
- property quality
- supply
- demand
- title
- project
- entry price.
Who May Benefit Most?
Markets with meaningful NRI-held resale inventory may experience:
slightly easier deal execution
rather than a measurable automatic price jump.
This can be relevant in established NRI/investor-heavy parts of:
- Mohali
- Aerocity
- Airport Road
- Sector 66/IT City belt
- Zirakpur
- Kharar.
But there is currently no basis to assign a specific appreciation percentage to the tax change.
What Changes for NRI Property Owners?
If an overseas owner is planning to sell after 1 October:
the buyer’s PAN-based compliance route may remove one objection buyers previously had:
“Mujhe TAN banana padega.”
That can make negotiation operationally easier.
But the NRI seller should still prepare:
- residency documentation
- PAN
- tax computation
- lower/nil deduction route where appropriate
- title/property records.
For NRI owners who are not ready to sell and need ongoing management:
NRI Property Management by PropKeyz
For documentary monitoring:
NRI Property Record Monitoring Tricity 2026
What Can PropKeyz Help With?
PropKeyz is a real-estate and property-management coordination brand.
PropKeyz can help organise the transaction/property side around:
- property assessment
- seller/buyer coordination
- property-document checklist
- inspection
- tenant/occupancy information
- society communication
- handover coordination
- local follow-up.
PropKeyz does not replace:
- Chartered Accountant
- tax adviser
- lawyer
- Sub-Registrar
- Income Tax Department.
For Tax
Use:
CA / tax professional
for:
- applicable withholding
- residential status
- lower/nil deduction
- current filing process.
For Title
Use:
qualified property lawyer
where legal title opinion is required.
PropKeyz Role
Property clarity + coordination + local execution support
rather than pretending every specialist issue is one service.
For the PropKeyz workflow:
Buying Property From an NRI in Mohali 2026: PropKeyz Analysis
The Buying Property From an NRI in Mohali 2026 story is important because one genuine compliance friction is about to disappear.
1. October 1 Is a Simplification—not a Tax Exemption
The headline change is:
TAN → PAN-based compliance.
The tax obligation remains.
2. The 1% Mistake Is the Biggest Buyer Risk
Buyer sees:
property sale
and assumes:
1%.
Seller residency must come first.
3. The ₹50 Lakh Threshold Should Not Be Imported Blindly
That threshold belongs to the resident-property provision.
4. Seller Residency Should Be Documented
Not verbally assumed.
5. Current Law Numbering Has Changed
Legacy Section 195 language remains useful for search and understanding, but current 2026 compliance sits under the Income-tax Act, 2025.
6. Lower TDS Can Matter Enormously for Seller Cash Flow
Current Form 128 / Section 395 process can be important where full withholding would materially exceed expected tax liability.
7. Portal Workflow Needs a Fresh Check on October 1
The law is changing before the existing portal guidance has fully caught up for non-resident deductees.
8. Tax Compliance Does Not Clean a Bad Title
A perfectly filed TDS transaction can still involve:
- title issue
- POA issue
- mortgage
- society dues.
9. The Reform Should Improve Liquidity More Than Price
The likely benefit is:
easier execution.
Not:
automatic rate appreciation.
10. NRI Resales Can Become Easier for Normal Retail Buyers
Removing the need for a one-off TAN reduces one point of friction for the specified buyer class.
Biggest Positive
A simpler PAN-based compliance path can make genuine NRI resale transactions easier for resident individual/HUF buyers to execute.
Biggest Risk
Buyers misunderstand the simplification and start applying the resident-seller 1% rule to NRI sellers.
PropKeyz View
The October 1 reform makes the process easier, not the due diligence optional. Verify residency, withholding, title, POA and property status before the money moves.
Buying Property From an NRI in Mohali 2026: Final Verdict
The Buying Property From an NRI in Mohali 2026 process changes materially on:
1 October 2026.
For a covered resident individual/HUF buyer:
separate TAN will no longer be required solely for TDS on consideration paid to a non-resident property seller.
That is good news.
But remember exactly what changed.
Changed
TAN requirement
Did Not Automatically Change
- seller’s non-resident status
- withholding obligation
- applicable tax computation
- title verification
- POA verification
- property due diligence.
Buyer Rule
PAN replaces TAN—not professional tax calculation.
Property Rule
Correct TDS ≠ Clear Title.
Final PropKeyz Rule
First verify who is selling, then verify how the payment is taxed, then verify what property you are actually buying.
Frequently Asked Questions
What changes when buying property from an NRI after 1 October 2026?
A resident individual/HUF buyer will no longer need a separate TAN solely for TDS on consideration paid for immovable property to a non-resident seller. The buyer will use a PAN-based reporting mechanism.
Does TDS disappear from 1 October 2026?
No.
Only the specified TAN requirement is removed.
Is TDS only 1% when buying property from an NRI?
No. The 1% property-TDS provision applies to qualifying resident-seller transactions. A non-resident seller falls under the non-resident withholding framework.
Does the ₹50 lakh property TDS threshold apply to an NRI seller?
Do not apply the resident-seller ₹50 lakh rule blindly to an NRI transaction. Non-resident taxable payments are governed separately.
Is Section 195 still applicable in 2026?
“Section 195” is the familiar legacy terminology under the former Income-tax Act, 1961. The Income-tax Act, 2025 has been effective since 1 April 2026, with the current equivalent framework mainly under Sections 393, 395 and 397.
How do I know if the property seller is an NRI?
Tax residential status must be determined under the Income Tax residency rules for the relevant tax year. Citizenship, Aadhaar or foreign residence alone are not enough.
When should TDS be planned?
Before any significant payment is released.
Can an NRI seller obtain lower TDS?
Yes, where conditions justify it, the current law provides a lower/nil-deduction certificate mechanism.
Is Form 13 still used?
Under the current Income-tax Rules, 2026, the corresponding lower/nil-deduction application is Form 128, replacing the old Form 13 terminology.
Can the buyer ask the tax department to determine the taxable portion?
Current rules provide Form 15E under Section 395(2) for determination of the appropriate chargeable proportion in applicable non-resident payment cases.
Is the new PAN filing workflow already live on 24 September 2026?
The reform is effective from 1 October. As of 24 September, the current e-filing Form 141 help still states that it does not apply where the deductee is non-resident. Buyers should check the updated live process on or after 1 October.
Can I buy NRI property through a Power of Attorney?
A sale can involve a properly authorised representative, but the POA’s authenticity, scope, validity and authority to sell should be professionally verified.
Does paying TDS prove the property’s title is clean?
No.
Tax compliance and property-title due diligence are separate.
Will this October 1 rule increase Mohali property rates?
There is no basis to claim a direct rate increase. The change reduces transaction friction and may make NRI resales easier to execute.
Continue Your PropKeyz Research
NRI Property Record Monitoring Tricity 2026
Check mutation, deeds, litigation and property records before relying only on an old ownership file.
NRI Property Record Monitoring Tricity 2026
Mohali NRI Property Protection 2026
Understand remote ownership, POA, inspections and property-protection systems.
Mohali NRI Property Protection 2026
NRI Property Management
For overseas owners who need local coordination, rent tracking, inspections and property care.
NRI Property Management by PropKeyz
Property Management Company in Mohali
For Mohali-specific rental and owner-management support.
Property Management Company in Mohali 2026
Property Inspection & Reporting
Useful when buying or managing a property remotely and you need current on-ground visual information.
Property Inspection & Reporting
CLU in Mohali 2026
For project/property land-use and approval due diligence.
How PropKeyz Works
See the PropKeyz assessment, onboarding and coordination process.
Buying or Selling an NRI-Owned Property in Mohali?
Before paying a token or scheduling registration, send PropKeyz:
Property Location:
Sector / Society:
Property Type:
Seller Resident / NRI?:
Seller Country:
Seller PAN Available?:
Seller Signing Personally / POA?:
Quoted Price:
Loan / Mortgage?:
Tenant / Vacant?:
Society Dues Clear?:
Lower TDS Certificate Available?:
Buyer Needs: Purchase / Due-Diligence Coordination / Property Inspection
PropKeyz can help organise the property side around:
- current property status
- seller/property-document checklist
- inspection
- society coordination
- tenant/possession status
- local transaction coordination.
For:
- TDS rate
- withholding calculation
- tax residency
- lower/nil certificate
- tax filing
use a qualified CA/tax adviser.
For:
- legal title opinion
- POA validity
- agreement drafting
- legal dispute
use an appropriate property lawyer.
Call / WhatsApp
+91 80534 69929
Suggested WhatsApp Message
Hi PropKeyz, I am evaluating an NRI-owned property in ________, Mohali. The seller currently lives in . Property price is ₹ and the transaction is planned for ________. I need help organising the property documents, inspection, seller/POA information and due-diligence checklist before I proceed.
Find it. Love it. Unlock it.
Your Property. Our Responsibility.
EXTERNAL SOURCES & OUTBOUND LINKS
Income Tax Department — Budget 2026 FAQ
Primary official source for:
- present TAN requirement
- removal of TAN requirement
- PAN-based reporting
- 1 October 2026 effective date.
Income Tax Department — Budget 2026 FAQ: No TAN for NRI Property Seller Transactions
Income-tax Act, 2025
Used to verify:
- current law effective from 1 April 2026.
Income-tax Act, 2025 — Official Text
Section 393 — Current TDS Framework
Used for:
- resident-property deduction
- non-resident payments
- rates-in-force framework.
Income Tax Department — Section 393
Section 397 — PAN / TAN Compliance
Used for the current statutory TAN exemption framework.
Income Tax Department — Section 397
Lower / Nil Deduction — Form 128
Used to verify the current replacement for former Form 13.
Income Tax Department — Form 128 FAQs
Seller Residential Status
Used to verify that residency is determined under Income Tax residency rules.
Income Tax Department — Residential Status Guide
Current NRI Property Tax Guidance
Used for current long-term/short-term tax-rate context.
Income Tax Department — NRI Immovable Property TDS FAQ
DISCLAIMER
This article is intended for:
- property buyer education
- NRI property transaction awareness
- general due diligence.
It is not:
- tax advice
- legal advice
- TDS computation
- title certification
- investment advice.
The tax treatment of an NRI property transaction can depend on:
- seller’s tax residential status
- transaction date
- holding period
- taxable gain
- tax rates in force
- surcharge/cess
- lower/nil-deduction certificate
- buyer type
- seller type
- current Income Tax portal/process.
The PAN-based TAN exemption discussed in this article becomes effective:
1 October 2026
for the specified class of buyer.
Because the operational portal workflow is changing, buyers should verify the live Income Tax process at the time of payment.
PropKeyz does not provide:
- tax filings
- legal title opinions
- lower-TDS certificates
- guaranteed transaction outcomes.
Use:
- CA/tax professional for tax
- qualified lawyer for title/legal matters.
About PropKeyz
PropKeyz Editorial Team
PropKeyz tracks Mohali and Tricity property markets with a focus on:
- property buying
- resale due diligence
- NRI ownership
- property management
- title/document awareness
- inspections
- GMADA/RERA/property regulation.
PropKeyz also supports NRI, outstation and local owners through:
- property management
- property inspections
- tenant coordination
- rent tracking
- maintenance coordination
- structured owner reporting.
Our transaction-research rules are:
Indian Citizen ≠ Automatically Indian Tax Resident
PAN ≠ TAN
PAN Replaces TAN ≠ TDS Removed
Resident Seller TDS ≠ NRI Seller TDS
Correct TDS ≠ Clear Property Title
POA Holder ≠ Property Owner
Tax Compliance ≠ Property Due Diligence
Find it. Love it. Unlock it.
Your Property. Our Responsibility.