Last Updated: 26 September 2026
Fact-Checked: 26 September 2026
The GMADA ₹6400 Crore Fund Case 2026 has added a major new financial-governance dimension to Greater Mohali’s rapidly expanding land-acquisition and infrastructure story.
The Punjab & Haryana High Court has asked the Punjab Government to explain the treatment of:
₹6,400 crore
deposited by the Greater Mohali Area Development Authority, or GMADA, with the State Treasury during financial year 2025-26.
Punjab Accountant-General Kumar Abhay told the High Court that this money should have remained in the State’s public accounts as a:
dedicated fund
because it was linked to obligations under Section 10(3) of the Right to Fair Compensation and Transparency in Land Acquisition, Rehabilitation and Resettlement Act, 2013.
His position was that absorbing the ₹6,400 crore into the:
State Consolidated Fund
to finance general budgetary deficits amounted to:
“serious accounting impropriety.”
But that is not the only position before the Court.
Punjab’s Advocate-General defended the State and GMADA, arguing that the treatment was lawful.
The State reportedly said that since the introduction of the 2013 land-acquisition law, it had spent approximately:
₹94,443 crore
on measures relating to food-security enhancement and that the accounting treatment of the ₹6,400 crore involved:
no impropriety.
The High Court has not yet delivered a final ruling on which interpretation is legally correct.
Instead, it has asked the respondents to file a specific affidavit explaining:
- whether the ₹6,400 crore could legally be absorbed into the Consolidated Fund;
- what amount GMADA is actually required to appropriate under Section 10(3);
- the justification for large Aerotropolis borrowings;
- the reason for the reported proposed payment of roughly ₹191 crore to a private entity connected with arranging financing.
The matter has been deferred to:
28 September 2026.
For a Greater Mohali property buyer, the correct question is therefore not:
“GMADA ke ₹6,400 crore gayab ho gaye?”
and it is also not:
“Aerotropolis cancel ho raha hai?”
Neither conclusion is supported by the current record.
The more useful questions are:
What exactly is the statutory purpose of the ₹6,400 crore?
What is the difference between a dedicated fund and the Consolidated Fund?
Why is Aerotropolis borrowing being examined in the same proceedings?
Does the case affect ongoing GMADA land acquisition?
Could it affect future infrastructure execution?
What should plot buyers, landowners and investors actually monitor?
This PropKeyz guide separates:
- confirmed facts,
- the Accountant-General’s view,
- Punjab’s defence,
- PIL allegations,
- court questions,
- Aerotropolis implications,
- buyer assumptions.
For the separate financing story around GMADA’s proposed ₹15,000-crore debt programme, read our detailed guide:
GMADA ₹15000 Crore Borrowing Plan 2026
Key Takeaways
- GMADA deposited approximately ₹6,400 crore with the Punjab State Treasury in FY 2025-26.
- Punjab Accountant-General Kumar Abhay told the High Court that the amount should have remained a dedicated fund.
- He described its absorption into the Consolidated Fund for general deficits as a serious accounting impropriety.
- That is the Accountant-General’s position—not yet a final finding of the High Court.
- Punjab’s Advocate-General disputes this interpretation.
- The State says its action and GMADA’s action were lawful.
- Punjab reportedly cited approximately ₹94,443 crore in food-security-related expenditure since the 2013 Act.
- The statutory issue relates to Section 10(3) of the RFCTLARR Act, 2013.
- Section 10(3) concerns safeguards where certain multi-crop irrigated land is acquired and requires agricultural/food-security compensation measures.
- The Court has asked Punjab to clarify whether the ₹6,400 crore could be absorbed into the Consolidated Fund.
- It has also asked what total amount GMADA is actually liable to appropriate under Section 10(3).
- The same proceedings contain questions about Aerotropolis borrowing.
- The PIL reportedly alleges an earlier ₹2,000-crore Aerotropolis loan was not utilised.
- That is a petitioner’s allegation, not an established finding.
- GMADA’s separate ₹15,000-crore borrowing programme is also under judicial scrutiny.
- The Court has sought clarification on a reported proposed ₹191-crore payment connected with securing the financing.
- The current material does not establish that the ₹15,000-crore programme has been cancelled.
- It does not establish that Aerotropolis acquisition has stopped.
- Official GMADA records continue to confirm acquisition activity across Aerotropolis pockets.
- Buyer due diligence should remain property-specific.
- The next important hearing is 28 September 2026.
PropKeyz View
The ₹6,400-crore story is currently a fund-purpose and accounting dispute before the High Court—not proof that Greater Mohali development has stopped or that every GMADA project is financially unsafe.
GMADA ₹6,400 Crore Fund Case 2026: Quick Answer
The GMADA ₹6,400 Crore Fund Case 2026 concerns a dispute over how money deposited by GMADA with the Punjab Government should legally and financially be treated.
Current Position — 26 September 2026
| Question | Current Position |
|---|---|
| Amount at issue | ₹6,400 crore |
| Depositor | GMADA |
| Financial year | 2025-26 |
| Main statutory provision | Section 10(3), RFCTLARR Act 2013 |
| Accountant-General position | Should remain a dedicated fund |
| State treatment questioned | Absorption into Consolidated Fund |
| AG description | “Serious accounting impropriety” |
| Punjab Government position | No impropriety; action lawful |
| State food-security expenditure cited | ₹94,443 crore |
| Final HC ruling on legality? | No |
| Court has sought | Specific affidavit / clarification |
| Aerotropolis borrowing questioned? | Yes |
| ₹15,000 Cr financing cancelled? | No such finding |
| Aerotropolis acquisition stopped? | No such finding |
| Next listed hearing | 28 September 2026 |

Direct Answer
The High Court has not ruled that Punjab illegally diverted ₹6,400 crore. The Accountant-General has challenged the accounting treatment, the State disputes that position, and the Court has asked for a detailed explanation.
PropKeyz Rule
Accounting Objection ≠ Final Judicial Finding
What Exactly Is the ₹6,400 Crore GMADA Fund Case?
At the centre of the dispute is money deposited by GMADA with the Punjab State Treasury.
The Accountant-General’s position is that the money was linked to:
Section 10(3) of the 2013 land-acquisition law
and was therefore meant for a specific statutory purpose related to:
agriculture and food security.
The dispute is essentially about whether the money should have remained:
ring-fenced / dedicated
or whether the State could account for it within:
the Consolidated Fund
while relying on its wider food-security expenditure.
This distinction may sound technical.
For property buyers, however, it is part of a bigger question:
How is money connected with large-scale land acquisition being accounted for when GMADA is simultaneously seeking massive new financing for future Mohali expansion?
What Did the Accountant-General Tell the High Court?
Punjab Accountant-General Kumar Abhay reiterated before the Court that the:
₹6,400 crore
was liable to be kept as a:
dedicated fund.
He objected to its absorption into the State’s Consolidated Fund for financing general budgetary deficits.
The Accountant-General also disputed the State’s argument that its historic expenditure on food security could effectively justify the treatment of the ₹6,400 crore.
According to the reported court proceedings, his office said the wider historic spending could not substitute for the requirement attached to this particular deposit.
Important
This is a professional/accounting position placed before the Court.
It is not yet:
a final declaration of illegality by the High Court.
PropKeyz Rule
AG Objection = Material Evidence Before Court
but:
AG Objection ≠ Final Judgment
What Is Punjab Government’s Defence?
A credible property-research article must include the State’s defence.
Punjab’s Advocate-General argued that:
- the State’s action was lawful;
- GMADA’s action was lawful;
- keeping the amount separately in the Public Account was not necessary.
The State also reportedly said it had invested approximately:
₹94,443 crore
for enhancing food security since the 2013 Act came into force.
Its argument is therefore broadly:
the State has already spent substantially on the statutory policy objective, and using the ₹6,400 crore through the Consolidated Fund does not amount to accounting impropriety.
Why This Matters
The dispute is not:
“AG says X, therefore X is finally proved.”
It is:
AG interpretation vs State interpretation → High Court clarification
PropKeyz View
For buyers, the correct approach is to follow the judicial outcome—not choose whichever headline sounds more dramatic.
What Has the High Court Actually Decided?
As of 26 September 2026, the Court has not finally decided the central accounting question.
It has asked the respondents to provide a:
specific affidavit.
The Court wants clarification on whether:
the ₹6,400 crore deposited for the distinct purpose contemplated under Section 10(3) could be absorbed into the Consolidated Fund to finance general budgetary deficits.
It has also asked:
what is the total amount liable to be appropriated by GMADA under Section 10(3)?
The Court further asked for explanation concerning:
- large Aerotropolis borrowings;
- the proposed ₹191-crore private-entity payment linked to securing financing.
What the Court Has Not Said
The Court has not currently said:
- GMADA is insolvent;
- ₹6,400 crore was stolen;
- the ₹15,000 crore loan is illegal;
- Aerotropolis is cancelled;
- existing plot allotments are invalid;
- all current acquisition must stop.
PropKeyz Rule
Court Question ≠ Court Conclusion
What Is Section 10(3) of the 2013 Land Acquisition Act?
This is the legal provision at the centre of the ₹6,400-crore dispute.
The Right to Fair Compensation and Transparency in Land Acquisition, Rehabilitation and Resettlement Act, 2013 includes a special provision for safeguarding food security.
The official law can be accessed through:
India Code — RFCTLARR Act, 2013
Section 10 concerns situations involving:
multi-crop irrigated land.
Broadly, Section 10(3) provides that when such land is acquired under the relevant provision, either:
- an equivalent area of culturable wasteland should be developed for agricultural purposes;
or:
- an amount equivalent to the value of the acquired land should be deposited with the appropriate Government for investment in agriculture for enhancing food security.
Why This Matters in the GMADA Case
The petitioners’ case and the Accountant-General’s position are linked to:
how money representing that statutory obligation should be held and used.
Important
PropKeyz is not saying:
every rupee GMADA has ever deposited is governed by Section 10(3).
The current High Court proceedings are precisely examining the applicable amount and its treatment.
Why Is Food Security Connected to GMADA Land Acquisition?
Urban development frequently requires conversion of land from:
agricultural use
to:
urban infrastructure / residential / commercial / institutional use.
When multi-crop irrigated land is acquired, Parliament created additional safeguards so the impact on agricultural production and food security is not ignored.
That means a large urban-development authority such as GMADA can encounter two financial obligations at once:
Land Acquisition Cost
Payment connected with:
- land value,
- compensation,
- rehabilitation,
- statutory benefits.
Food-Security Safeguard
Additional statutory treatment where the specific Section 10 conditions apply.
Property Lesson
This shows why:
land acquisition cost is not simply “rate per acre × acres acquired.”
Large public development can involve:
- compensation,
- rehabilitation,
- statutory deposits,
- infrastructure,
- litigation,
- financing cost.
Dedicated Fund vs Consolidated Fund
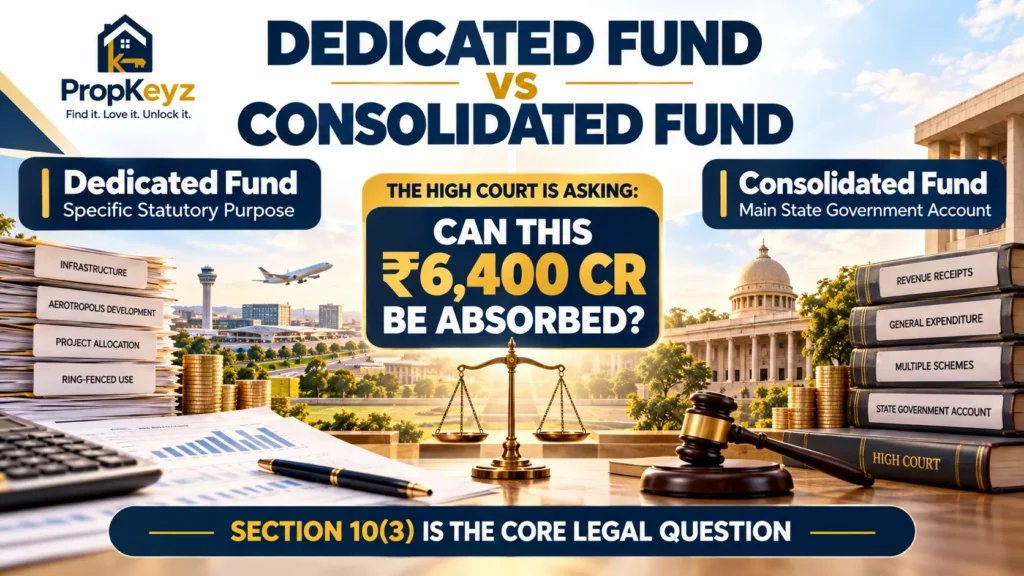
This distinction is central to the case.
Dedicated Fund
In the Accountant-General’s interpretation, the money should be:
earmarked for a specific statutory purpose.
Think:
Purpose A → Money reserved for Purpose A
Consolidated Fund
The Consolidated Fund is the main constitutional account into which major government revenues and borrowings are credited and from which expenditure is authorised through the budgetary process.
The Current Dispute
The key question is broadly:
Can money deposited for the specific Section 10(3) purpose be absorbed into the general Consolidated Fund when the State says it is already spending heavily on food security?
The High Court has asked Punjab to explain.
PropKeyz Rule
Where the Money Sits Can Matter as Much as How Much Money Exists
Where Did the ₹6,400 Crore Come From?
The current reporting establishes that:
GMADA deposited ₹6,400 crore with the State Treasury during FY 2025-26.
The Court proceedings connect the sum with obligations under:
Section 10(3).
But PropKeyz should not invent a project-by-project breakup unless an official financial schedule establishes one.
Therefore we should not write:
“₹X crore came from Aerotropolis Pocket E.”
or:
“₹Y crore belongs to Sector 101.”
unless an official source confirms it.
PropKeyz Rule
Total Fund Figure ≠ Project-Wise Breakup
Is the ₹6,400 Crore Missing?
No current source reviewed by PropKeyz establishes that:
the ₹6,400 crore is “missing.”
The dispute is about:
accounting / legal treatment
and:
the purpose for which the amount should be held or used.
This is a critical distinction.
Incorrect Headline
“₹6,400 Cr GMADA money missing.”
Better Explanation
“High Court asks Punjab to justify accounting treatment of ₹6,400 Cr GMADA deposit.”
PropKeyz Rule
Accounting Treatment Dispute ≠ Missing Money
Is This a “GMADA Scam”?
PropKeyz should not use that label.
Why?
Because there is no final judicial finding currently establishing:
- fraud,
- criminal misappropriation,
- illegal diversion.
The PIL raises serious allegations.
The Accountant-General raises a serious accounting objection.
Punjab disputes those allegations and maintains the action was lawful.
The High Court is examining the issue.
Correct PropKeyz Language
Use:
- fund case,
- accounting dispute,
- High Court scrutiny,
- dedicated-fund question,
- financial-governance issue.
Avoid:
- scam,
- theft,
- fraud,
unless a competent authority or court later establishes those facts.
How Is the ₹15,000 Crore Borrowing Connected?
GMADA is also pursuing a large financing programme of approximately:
₹15,000 crore.
That programme is already covered in depth in:
GMADA ₹15000 Crore Borrowing Plan 2026
The proposed financing can involve:
- bonds,
- debentures,
- bank loans,
- other debt instruments.
The current High Court proceedings connect the two stories because the petitioners questioned:
- why such large new borrowing is required;
- project-wise financial need;
- repayment capacity;
- earlier Aerotropolis borrowings;
- arranger cost.
Important
The ₹6,400 crore article should not become a duplicate borrowing article.
The core question here is:
If GMADA previously deposited ₹6,400 crore with the State, how should that money legally be treated while GMADA is seeking further large-scale financing?
Why Already Having a ₹15,000 Crore Article Matters
From an SEO perspective, these pages should work together.
This Article
Primary search intent:
₹6,400 Cr dedicated fund + Section 10(3) + High Court
Existing Borrowing Article
Primary search intent:
₹15,000 Cr financing + land acquisition + borrowing structure
Correct Internal-Link Strategy
From this page, link:
“For the complete financing structure, read GMADA ₹15000 Crore Borrowing Plan 2026.”
From that page, reverse-link:
“For the latest ₹6,400 Cr dedicated-fund High Court issue, read GMADA ₹6,400 Crore Fund Case 2026.”
That gives Google a clear topical hierarchy instead of two overlapping pages.
What Is the Reported ₹2,000 Crore Aerotropolis Loan Allegation?
The PIL reportedly alleges that GMADA had earlier availed a:
₹2,000 crore
loan for the Aerotropolis project but that the amount was:
not utilised.
This must remain attributed to:
the petitioners.
PropKeyz has not independently established the allegation as a final fact.
Correct Wording
“The PIL alleges that an earlier ₹2,000-crore Aerotropolis loan was not utilised.”
Incorrect Wording
“GMADA wasted an earlier ₹2,000 crore loan.”
PropKeyz Rule
Petition Allegation ≠ Proven Financial Fact
What Is the ₹191 Crore Fund-Arranger Issue?
The High Court has also asked for clarification concerning approximately:
₹191 crore
proposed to be paid to a private entity in connection with arranging the ₹15,000-crore financing.
Your existing borrowing article already discusses the reported merchant-banker/fund-arranger arrangement.
For the complete structure, see:
GMADA ₹15000 Crore Borrowing Plan 2026
Current Legal Position
The Court has asked:
why this proposed cost is justified.
That does not mean:
the ₹191 crore is judicially declared unlawful.
Buyer Lesson
Financing has a cost.
The correct question is:
Does the financing cost make sense relative to the funds actually mobilised and the projects financed?
That is primarily a:
public-finance / authority-governance question
rather than a direct title question for an individual property buyer.
Why Is Aerotropolis Central to the Case?
Aerotropolis is one of GMADA’s biggest current expansion programmes.
It involves large-scale:
- land acquisition,
- land pooling,
- compensation,
- roads,
- utilities,
- future residential development,
- commercial/institutional planning.
That scale requires:
capital before development can be delivered.
Official GMADA records confirm active 2026 acquisition notifications across Aerotropolis Pockets:
- E,
- F,
- G,
- H,
- I,
- J.
For detailed land-acquisition context, read:
Mohali Aerotropolis Land Acquisition 2026
For current land-pooling developments:
Aerotropolis Land Pooling 2026
PropKeyz View
Aerotropolis is where land, compensation, borrowing and future property supply all meet—so financing scrutiny naturally matters to the development story.
What Is Actually Happening With Aerotropolis Acquisition?
Official GMADA notifications independently confirm active land-acquisition steps across multiple Aerotropolis villages and pockets.
The official GMADA notification portal can be checked here:
Examples during March/April 2026 include acquisition notifications for:
- Pocket E,
- Pocket F,
- Pocket G,
- Pocket H,
- Pocket I,
- Pocket J.
This independently supports the conclusion that:
Aerotropolis is an active statutory development programme.
Important
The existence of the High Court finance case does not by itself prove:
acquisition has stopped.
PropKeyz Rule
Financial Scrutiny ≠ Acquisition Cancellation
Does the High Court Case Stop Aerotropolis?
No such conclusion is supported by the current material.
The Court is asking questions relating to:
- fund treatment,
- borrowing justification,
- statutory appropriation,
- financing cost.
There is currently no reviewed order saying:
“Stop Aerotropolis.”
Buyer Warning
Do not act on WhatsApp claims such as:
“HC ne Aerotropolis rok diya.”
Verify:
- current GMADA notification,
- exact village,
- pocket,
- acquisition stage,
- land-pooling record.
PropKeyz Rule
Case Against Financing Treatment ≠ Stay on Entire Township
Does It Affect Aerotropolis Landowners?
Potentially the case matters at the broader:
finance / acquisition-policy level.
But it does not automatically change the legal status of every individual landowner.
A landowner should continue to check:
- acquisition notification,
- award,
- compensation,
- land-pooling choice,
- option form,
- LOI,
- litigation specific to the land.
For the detailed acquisition background:
Mohali Aerotropolis Land Acquisition 2026
PropKeyz Rule
Authority-Finance Case ≠ Automatic Change to Individual Compensation Rights
Does It Affect Aerotropolis LOI / Land Pooling Rights?
The current ₹6,400-crore proceedings do not by themselves establish that:
- LOIs are cancelled,
- land-pooling rights are invalid,
- entitlements have disappeared.
Current Aerotropolis land-pooling research should therefore remain separate.
For that topic, use:
Aerotropolis Land Pooling 2026
Buyer Caution
If someone is selling:
“future GMADA plot rights”
or an:
LOI-linked interest
the buyer should verify:
- underlying landowner,
- pocket,
- entitlement,
- option,
- LOI,
- transferability,
- development stage.
Do not buy only because:
“GMADA ka bada project hai.”
Does It Affect Existing GMADA Plot Owners?
Not automatically.
Owners in established GMADA schemes such as:
- Aerocity,
- IT City,
- Eco City,
- developed sectors
should not assume that their:
- title,
- allotment,
- transfer,
- possession
has become invalid because of this finance case.
Property-level rights still depend on:
- allotment documents,
- authority ledger,
- dues,
- transfer status,
- property-specific litigation.
Example — IT City
A completely separate issue exists in Sector 83 Alpha concerning the earlier ₹7,845/sq-yd enhancement demand.
Read:
IT City Sector 83 Alpha Mohali 2026
That case concerns:
allottee liability + natural justice
not:
the ₹6,400-crore dedicated fund.
PropKeyz Rule
One GMADA Case ≠ Every GMADA Property Case
Could Infrastructure Projects Be Delayed?
This is currently an:
open risk question
rather than a confirmed outcome.
Large-scale authority development depends on:
- available funds,
- land possession,
- contractor execution,
- approvals,
- court proceedings,
- utility coordination.
If financing is:
- delayed,
- restructured,
- reduced,
some implementation timelines could potentially be affected.
But PropKeyz should not publish:
“The ₹6,400 crore case will delay Aerotropolis roads.”
There is no reviewed evidence establishing that specific outcome.
Better Wording
“Financial and judicial scrutiny can become one factor to monitor in the implementation timeline, but project-specific delay must be separately verified.”
For wider Mohali infrastructure context, see:
Mohali Power Infrastructure 2026
Does GMADA Borrowing Mean Financial Distress?
Borrowing by itself does not prove:
financial distress.
Large urban authorities may borrow because major development requires:
large upfront capital expenditure.
The relevant questions are:
- how much is borrowed?
- on what terms?
- for which projects?
- how is repayment planned?
- what assets/revenues support it?
- what is the financing cost?
Incorrect Logic
“GMADA borrowing ₹15,000 crore means GMADA has no money.”
Better Logic
“GMADA is seeking significant external financing during a capital-intensive expansion cycle; repayment and project allocation therefore matter.”
For the full borrowing analysis:
GMADA ₹15000 Crore Borrowing Plan 2026
Can GMADA Still Run Auctions?
There is currently no basis to conclude that:
GMADA auctions are generally frozen.
GMADA’s authority functions include multiple separate activities:
- acquisition,
- planning,
- auctions,
- allotments,
- transfer,
- infrastructure.
A fund-treatment case does not automatically shut down every authority function.
For current market context around one of Mohali’s largest mixed-use locations, read:
PropKeyz Rule
Authority Under Scrutiny ≠ Authority Closed for Business
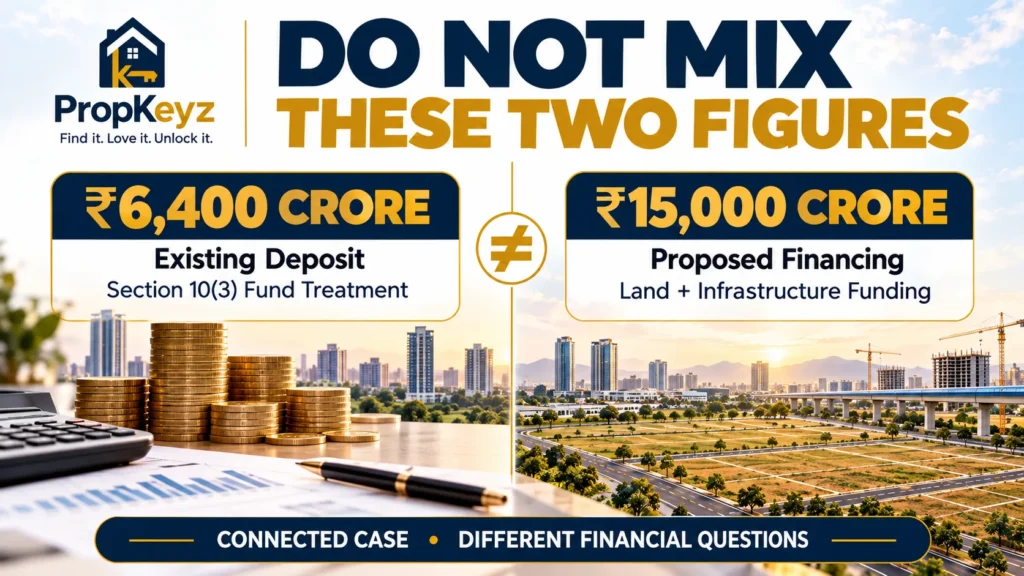
GMADA ₹6,400 Cr Fund Case vs ₹15,000 Cr Borrowing Plan
| Issue | ₹6,400 Cr Fund Case | ₹15,000 Cr Borrowing Plan |
|---|---|---|
| Main question | Treatment of existing deposited funds | Raising future financing |
| Core law/context | Section 10(3) / food security | Debt / infrastructure finance |
| High Court involvement | Yes | Yes |
| Accountant-General issue | Central | Relevant through wider scrutiny |
| Aerotropolis connection | Indirect + court scrutiny | Direct financing context |
| Final ruling? | No | No |
| Borrowing cancelled? | N/A | No such finding |
| Property impact | Governance / execution monitoring | Financing / execution capacity |
| Best PropKeyz article | This page | Existing borrowing-plan article |
PropKeyz Rule
₹6,400 Cr ≠ ₹15,000 Cr
They answer different questions.
GMADA Fund Case vs IT City Enhancement Dispute
Another useful distinction:
| Issue | ₹6,400 Cr GMADA Fund Case | Sector 83 Alpha Enhancement |
|---|---|---|
| Main issue | Authority fund treatment | Plot-allottee additional demand |
| Amount | ₹6,400 Cr authority-level | ₹7,845/sq yd earlier demand |
| Buyer liability direct? | No automatic direct liability | Potential plot-level liability |
| Court issue | Accounting/statutory fund purpose | Natural justice / recovery procedure |
| Applies to all GMADA plots? | No | No |
| Buyer action | Monitor governance/execution | Check exact plot ledger/liability |
For the full Sector 83 Alpha analysis:
IT City Sector 83 Alpha Mohali 2026
Buyer Impact by Property Type
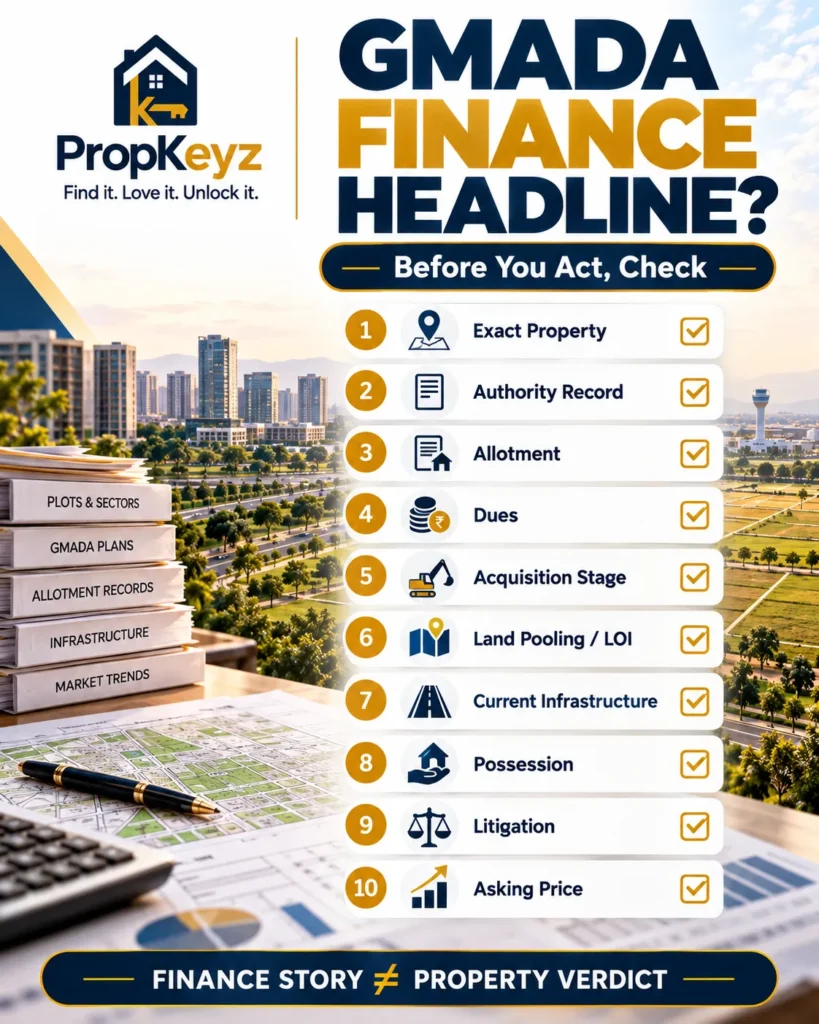
The ₹6,400-crore case affects different property types differently.
Existing GMADA Plot
Check:
- current allotment,
- dues,
- possession,
- transfer status.
Do not panic because of an authority-level finance case.
Aerotropolis Future Plot / LOI
Check:
- pocket,
- underlying land,
- option,
- entitlement,
- current acquisition stage.
Private Project Near Aerotropolis
Check:
- RERA,
- title,
- CLU,
- licence,
- access,
- approved infrastructure.
Do not value it only on:
future GMADA development.
Agricultural Land
Check:
- acquisition notification,
- Master Plan,
- land use,
- exact khasra,
- acquisition stage.
Commercial Property
Check:
- current demand,
- actual access,
- development stage,
- planned vs completed infrastructure.
PropKeyz Buyer Rule
Finance Story → Project Impact → Exact Property
Never jump directly from:
finance headline
to:
buy/sell decision.
NRI & Outstation Owner Perspective
NRI and outstation owners often receive market news through:
- WhatsApp groups,
- brokers,
- relatives,
- local dealers.
A headline such as:
“GMADA fund case High Court me”
can easily be converted into:
“property risk me hai.”
That is too broad.
Remote owners should distinguish:
Authority-Level News
- High Court case,
- fund treatment,
- borrowing.
from:
Property-Level Status
- title,
- allotment,
- possession,
- tenant,
- maintenance,
- dues.
PropKeyz supports eligible remote property owners with:
- inspection,
- local reporting,
- tenant coordination,
- maintenance coordination,
- photo/video updates.
Explore:
and:
PropKeyz Rule
Remote Owner Decisions Should Be Based on the Exact Property File—not market rumours.
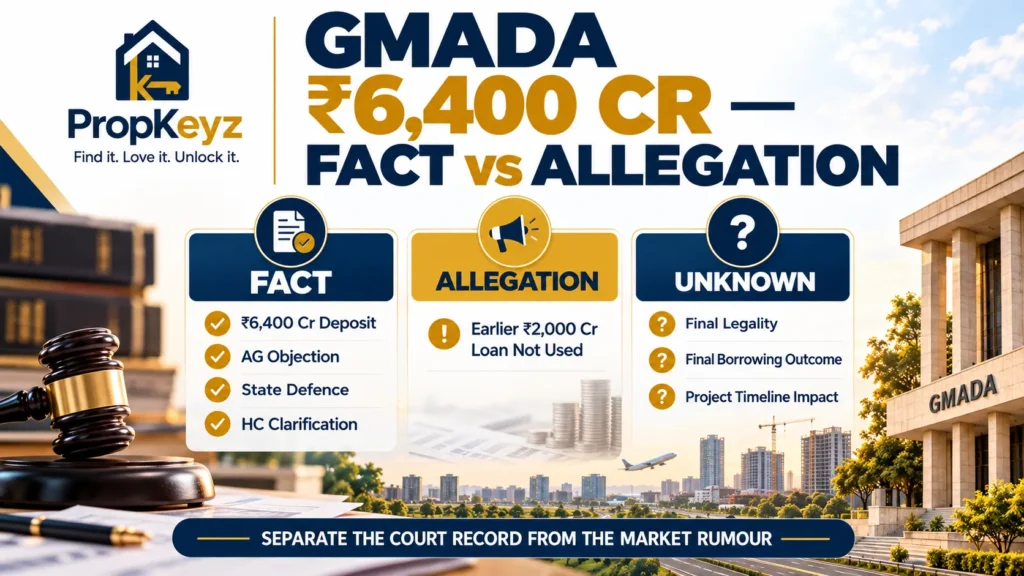
Confirmed Facts vs Allegations vs Unknowns
| Category | Current Position |
|---|---|
| GMADA deposited ₹6,400 Cr with State Treasury | Reported / confirmed in proceedings |
| AG says it should remain a dedicated fund | Confirmed position before Court |
| AG calls absorption serious accounting impropriety | Confirmed position |
| Punjab says treatment was lawful | Confirmed defence |
| Punjab cites ₹94,443 Cr food-security expenditure | Reported State submission |
| HC asks whether Consolidated Fund treatment is permissible | Confirmed |
| HC asks total Section 10(3) liability | Confirmed |
| ₹15,000 Cr financing under scrutiny | Confirmed |
| PIL says earlier ₹2,000 Cr Aerotropolis loan unused | Allegation |
| ₹191 Cr arranger cost questioned | Confirmed court query |
| ₹6,400 Cr “stolen” | Unsupported |
| ₹15,000 Cr loan cancelled | Unsupported |
| Aerotropolis cancelled | Unsupported |
| All GMADA plots unsafe | Unsupported |
| Infrastructure delay certain | Unknown |
| Final accounting legality | Awaiting further proceedings |
PropKeyz View
The strongest buyer research separates a Court question from a Court finding, and an allegation from an established fact.
What Buyers Should Monitor Next
The next High Court hearing is listed for:
28 September 2026.
After that hearing, check for:
1. Specific Affidavit
How does Punjab explain the:
₹6,400 crore?
2. Section 10(3) Liability
Does the State/GMADA disclose:
a total required amount?
3. Dedicated-Fund Question
Does the Court express a clearer view on:
Public Account vs Consolidated Fund treatment?
4. Aerotropolis Borrowing
What justification is filed for:
historic / proposed borrowing?
5. ₹191 Crore Arranger Cost
Is a detailed basis given?
6. Any Interim Direction
Does the Court:
- restrict borrowing,
- allow it,
- seek more records,
- defer again?
PropKeyz Update Rule
Update the same URL after every material hearing. Do not publish a new duplicate article.
How Should a Mohali Buyer Evaluate the Story?
Use five layers.
Layer 1 — Authority-Level Issue
What is the High Court actually examining?
Layer 2 — Project
Is your property connected to:
- Aerotropolis,
- IT City,
- Aerocity,
- another GMADA sector?
Layer 3 — Property Stage
Are you buying:
- developed plot,
- allotment,
- LOI,
- land under acquisition,
- private RERA project?
Layer 4 — Current Documentation
Verify:
- title,
- allotment,
- dues,
- transfer,
- possession.
Layer 5 — Pricing
Has the seller priced in:
future infrastructure that does not exist yet?
PropKeyz Formula
Exact Property → Legal Status → Authority Record → Development Stage → Current Infrastructure → Price → Exit Liquidity
For wider Mohali buying options:
PropKeyz Analysis
The GMADA ₹6,400 Crore Fund Case 2026 is important because it brings Greater Mohali’s development-finance model into judicial focus at the same time that GMADA is expanding on an unusually large scale.
1. This Is Fundamentally a Governance Question
The key issue is:
how money linked to a statutory purpose should be accounted for.
That is different from:
whether GMADA has active projects.
2. The Accountant-General’s Objection Is Significant
Calling the treatment a:
serious accounting impropriety
is not a minor observation.
It gives the High Court a concrete professional accounting position to examine.
3. But Punjab Has a Substantive Defence
The State says:
- it has invested substantially in food security;
- the accounting treatment is lawful;
- separate earmarking is unnecessary.
A responsible article must carry both.
4. Section 10(3) Is the Real Legal Core
The article should not become only:
₹6,400 crore headline content.
The real question is:
what does the 2013 Act require when qualifying agricultural land is acquired?
5. Aerotropolis Makes the Case Property-Relevant
Without Aerotropolis, this might remain mainly:
public-accounting news.
But Aerotropolis links the dispute with:
- land acquisition,
- compensation,
- borrowing,
- future urban development.
6. The ₹15,000 Crore Question Is Separate—but Connected
GMADA may need large capital for its expansion.
At the same time, the Court is asking why such financing is required when another very large amount had already been deposited with the State.
That makes:
financial transparency
part of the urban-development discussion.
7. The Case Does Not Yet Justify Buyer Panic
There is no present basis to say:
every GMADA asset is risky.
Authority-level finance and property-level title are different questions.
8. Future Infrastructure Premium Needs More Discipline
A buyer paying a major premium because:
“Aerotropolis me sab infra aa raha hai”
should ask:
- what is funded?
- what is acquired?
- what is tendered?
- what is under construction?
- what is operational?
9. Financing Capacity Can Help Development
If GMADA mobilises financing lawfully and deploys it efficiently, it can help move:
- acquisition,
- roads,
- utilities,
- development
forward.
10. Borrowing Also Creates Accountability
A ₹15,000-crore borrowing programme requires scrutiny of:
- cost,
- project allocation,
- repayment,
- execution.
That is normal for a financing programme of this size.
11. The Next Hearing Matters More Than Speculation
The September 28 hearing can materially change:
- legal interpretation,
- disclosure,
- borrowing status.
12. Keep Property Decisions Parcel-Specific
The biggest PropKeyz takeaway remains:
authority headline ≠ individual property verdict.
Final PropKeyz Analysis
The ₹6,400-crore GMADA fund case is a significant governance and public-finance issue because the High Court is examining whether money tied to a statutory food-security purpose could be absorbed into Punjab’s Consolidated Fund while GMADA simultaneously seeks major new financing for Greater Mohali expansion. But the current proceedings do not establish that the money was unlawfully diverted, that the ₹15,000-crore borrowing is cancelled, or that Aerotropolis development has stopped. Buyers should monitor the court record while continuing to evaluate each property through its own title, authority status, acquisition stage, infrastructure and price.
PropKeyz Verdict: GMADA ₹6,400 Crore Fund Case 2026
The strongest interpretation today is:
serious questions have been raised—but they have not yet become final judicial findings.
Confirmed
- ₹6,400 crore deposit;
- Accountant-General objection;
- Punjab Government defence;
- High Court clarification;
- Aerotropolis borrowing scrutiny;
- ₹191-crore query;
- September 28 next hearing.
Not Confirmed
- illegal diversion;
- missing money;
- loan cancellation;
- Aerotropolis cancellation;
- blanket GMADA buyer risk.
For Existing GMADA Owners
Check your:
exact property file
rather than reacting to authority-level headlines.
For Aerotropolis Buyers / Landowners
Track:
acquisition + land pooling + financing + infrastructure
as separate stages.
For Investors
Do not pay today for:
fully completed future infrastructure
unless that infrastructure actually exists.
Final PropKeyz Rule
Track the money—but buy the property only after verifying the land, authority record, development stage and real infrastructure serving that exact asset.
Frequently Asked Questions
What is the GMADA ₹6,400 Crore Fund Case 2026?
It concerns the High Court’s examination of the accounting treatment of ₹6,400 crore deposited by GMADA with the Punjab State Treasury.
Why is ₹6,400 crore under scrutiny?
Punjab’s Accountant-General says the money was linked to Section 10(3) of the 2013 land-acquisition law and should have remained a dedicated fund.
Has the High Court said the money was illegally diverted?
No final judicial finding to that effect has been made as of 26 September 2026.
What does Punjab Government say?
Punjab says its action and GMADA’s action were lawful and that no impropriety occurred.
Why has Punjab mentioned ₹94,443 crore?
The State reportedly cited approximately ₹94,443 crore spent over 12 years on food-security enhancement to support its defence.
What is Section 10(3)?
It is part of the RFCTLARR Act’s food-security safeguards concerning certain multi-crop irrigated land acquisitions.
Does Section 10(3) require money to be kept separately?
The current dispute includes precisely this question of statutory and accounting treatment.
What is a dedicated fund?
A dedicated fund is money earmarked for a defined purpose.
What is the Consolidated Fund?
It is the State’s principal constitutional account for receipts and authorised expenditure.
Is ₹6,400 crore missing?
No reviewed source establishes that the money is “missing.”
Is this a scam?
PropKeyz does not use that label because there is no final finding establishing fraud or criminal wrongdoing.
How is the ₹15,000 crore borrowing connected?
The High Court has also sought clarification around GMADA’s large proposed financing and Aerotropolis borrowing.
Has GMADA already received the entire ₹15,000 crore?
Current reviewed material does not establish that the full amount has already been mobilised.
What is the earlier ₹2,000 crore Aerotropolis loan?
The PIL alleges an earlier ₹2,000-crore loan was availed but not utilised. It remains an allegation in the petition.
What is the ₹191 crore issue?
The Court has asked why approximately ₹191 crore is proposed to be paid to a private entity in connection with securing the large financing.
Has the ₹191 crore been declared illegal?
No.
Is Aerotropolis cancelled?
No such conclusion is supported.
Has Aerotropolis land acquisition stopped?
Official GMADA records continue to show active acquisition processes.
Are Aerotropolis LOIs cancelled?
No current material establishes a blanket cancellation.
Does this affect Aerocity plots?
There is no automatic direct title impact merely because GMADA is facing an authority-level fund case.
Does this affect IT City plots?
Not automatically. IT City also has separate property-specific issues such as the Sector 83 Alpha enhancement dispute.
Can GMADA still auction property?
Current material does not establish a general freeze on GMADA auctions.
Will the case delay infrastructure?
Possible project-specific implications should be monitored, but no blanket delay has been established.
Should I avoid all GMADA property?
The current proceedings do not support such a blanket conclusion.
What should an Aerotropolis buyer verify?
Verify:
- pocket,
- acquisition stage,
- landowner,
- LOI,
- land-pooling entitlement,
- transferability,
- current infrastructure.
What should an existing GMADA plot owner verify?
Check:
- allotment,
- authority dues,
- possession,
- transfer record,
- property-specific litigation.
When is the next hearing?
The current matter has been listed for:
28 September 2026.
What should PropKeyz update after the next hearing?
Update:
- High Court directions,
- Punjab affidavit,
- Section 10(3) amount,
- borrowing position,
- Aerotropolis implications.
What is the safest buyer rule?
Do not convert an authority-level finance headline into a property decision until you verify how, if at all, it affects your exact asset.
Continue Your Greater Mohali Property Research
GMADA ₹15000 Crore Borrowing Plan 2026
For the complete financing structure, debt instruments, land-acquisition context and borrowing risks:
Read GMADA ₹15000 Crore Borrowing Plan 2026
Mohali Aerotropolis Land Acquisition 2026
For detailed acquisition-stage research:
Read Mohali Aerotropolis Land Acquisition 2026
Aerotropolis Land Pooling 2026
For current landowner options and entitlement analysis:
Read Aerotropolis Land Pooling 2026
IT City Sector 83 Alpha Mohali 2026
For the ₹7,845/sq-yd enhancement-demand dispute:
Read IT City Sector 83 Alpha Mohali 2026
Mohali Power Infrastructure 2026
For wider Greater Mohali infrastructure capacity:
Read Mohali Power Infrastructure 2026
Sector 62 Mohali 2026
For current GMADA mixed-use auction and City Centre development context:
Explore Property in Mohali
For current residential opportunities across Mohali:
Property Buyer & Owner Support Through PropKeyz
PropKeyz focuses on practical property research, buyer comparisons and owner support across:
- Mohali,
- Chandigarh,
- Panchkula,
- Zirakpur,
- New Chandigarh,
- Kharar,
- nearby Tricity markets.
Buying in a GMADA Sector?
Compare:
- exact authority status,
- allotment/ownership record,
- dues,
- current development,
- effective buyer cost,
- future infrastructure claims.
Buying Near Aerotropolis?
Do not compare only:
distance from airport
or:
future GMADA map.
Verify:
- legal asset,
- actual access,
- acquisition status,
- RERA where applicable,
- infrastructure stage.
NRI / Outstation Owner?
PropKeyz provides eligible owner-support services such as:
- local inspection,
- photo/video reporting,
- tenant coordination,
- maintenance coordination,
- structured owner updates.
Explore NRI Property Management
Discuss a Property
Share:
- exact location,
- property type,
- asking price,
- authority status,
- possession stage,
- end-use objective.
Your Property. Our Responsibility.
Sources & Verification
This article was last fact-checked on:
26 September 2026
Hindustan Times — 26 September 2026
Used to verify:
- ₹6,400 crore deposit;
- Accountant-General position;
- State defence;
- ₹94,443 crore food-security expenditure claim;
- Section 10(3) issue;
- September 28 hearing;
- Aerotropolis borrowing questions;
- ₹191 crore query;
- ₹2,000 crore PIL allegation.
External Source: Hindustan Times — ₹6,400 Cr GMADA Fund Report
The Tribune — 25 September 2026
Used as independent verification of:
- High Court request for explanation;
- dedicated-fund question;
- Accountant-General position;
- State defence;
- Section 10(3) context;
- Aerotropolis borrowing questions.
External Source: The Tribune — High Court Dedicated Fund Report
India Code — RFCTLARR Act, 2013
Used for the statutory framework around:
Section 10 — Special provision to safeguard food security
Read the RFCTLARR Act on India Code
GMADA Official Notifications
Used to verify current 2026 statutory acquisition activity across:
- Aerotropolis Pocket E,
- Pocket F,
- Pocket G,
- Pocket H,
- Pocket I,
- Pocket J.
View GMADA Official Notifications
PropKeyz — GMADA ₹15000 Crore Borrowing Plan 2026
Used for internal topical context concerning:
- debt programme;
- financing structure;
- land acquisition;
- fund arranger;
- project-finance questions.
Read GMADA ₹15000 Crore Borrowing Plan 2026
PropKeyz — Mohali Aerotropolis Land Acquisition 2026
Used for project-stage and acquisition context.
Read Mohali Aerotropolis Land Acquisition 2026
Disclaimer
This article is intended for:
- property research,
- market intelligence,
- land-acquisition education,
- buyer awareness.
It does not constitute:
- legal advice,
- accounting advice,
- government financial audit,
- property valuation,
- investment advice.
The High Court proceedings discussed above are:
ongoing.
As of 26 September 2026, the Court had not finally determined:
- whether the ₹6,400 crore accounting treatment was unlawful;
- what exact amount GMADA is liable to appropriate under Section 10(3);
- whether the ₹15,000-crore borrowing should proceed;
- whether the reported ₹191-crore financing cost is justified.
The ₹2,000-crore earlier Aerotropolis-loan issue discussed in this article is:
an allegation recorded from the PIL
and should not be treated as a final established fact unless subsequently proved or admitted.
Before purchasing a property linked to:
- GMADA,
- Aerotropolis,
- IT City,
- Aerocity,
- future GMADA development,
independently verify:
- title,
- allotment,
- acquisition stage,
- current authority record,
- dues,
- possession,
- approved development,
- RERA where applicable,
- infrastructure status,
- property-specific litigation.
PropKeyz does not guarantee:
- project completion,
- court outcome,
- infrastructure timeline,
- financing availability,
- property appreciation,
- resale liquidity.
Your Property. Our Responsibility.